


Tesla Arranges $30 Billion in Credit Lines for New Products
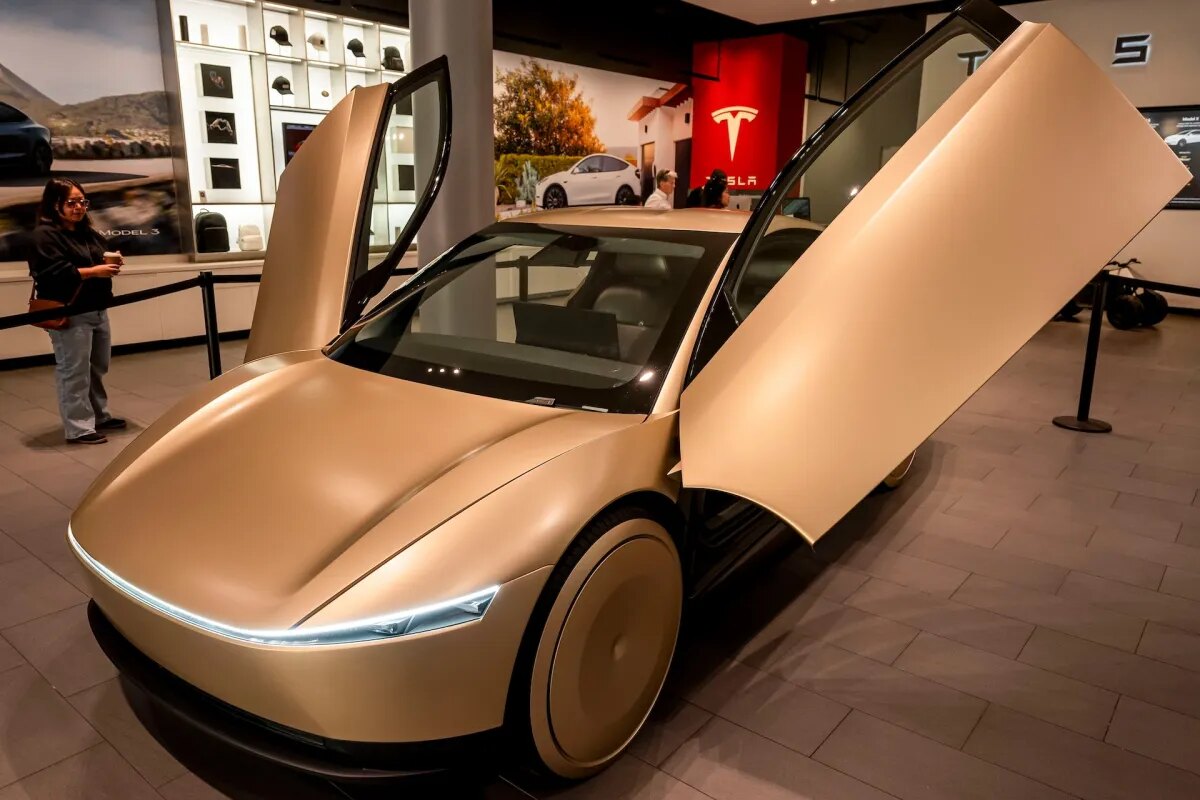
Tesla has secured $30 billion in new credit lines that could support the expansion of its Cybercab robotaxi, Optimus humanoid robot and Tesla Semi. The financing consists of a $20 billion three-year delayed-draw term loan facility agreed with Citibank, plus an $8 billion five-year revolving credit facility and a $2 billion revolving credit facility with a 364-day term from Wells Fargo.
The company disclosed the facilities in a regulatory filing and said it does not plan to draw on them during 2026. The agreements give Tesla access to additional financing while it develops products that require fresh manufacturing capacity.
Three facilities, $30 billion of capacity
Citibank's $20 billion facility is structured as a delayed-draw term loan, allowing Tesla to access it over its three-year term rather than taking the full amount immediately. The two Wells Fargo revolving facilities total $10 billion, with terms of five years and 364 days respectively.
Tesla ended the second quarter with about $9 billion in debt and more than $40 billion in cash and investments. It has also projected that capital expenditure will reach at least $25 billion in 2026, placing the new credit arrangements alongside a substantial planned investment programme.
Manufacturing is central to the expansion
The Cybercab, Optimus and Tesla Semi all require new manufacturing lines. For the Semi and Optimus, Tesla has chosen to build dedicated factories, making production build-out a central element of the company’s effort to take the products from development into scale.
The financial backdrop connects with Tesla delays Cybercab, Semi and Megapack launches because the timing of Cybercab, Semi and Megapack launches is linked to rising expenditure and pressure on profitability. The newly arranged facilities do not alter Tesla’s statement that it will not draw on them this year, but they provide borrowing capacity as manufacturing work advances.
What the financing means for businesses
For businesses following large industrial technology programmes, Tesla’s approach illustrates the value of arranging financing capacity before it is needed. The distinction between securing credit and drawing it matters: committed facilities can preserve flexibility while capital-intensive factories and production lines are being built.
With at least $25 billion in projected 2026 capital expenditure, Tesla’s credit lines place funding options beside its existing cash and investments. The practical implication is that companies planning new production assets should align financing arrangements with the long lead times and investment demands of their manufacturing roadmap.